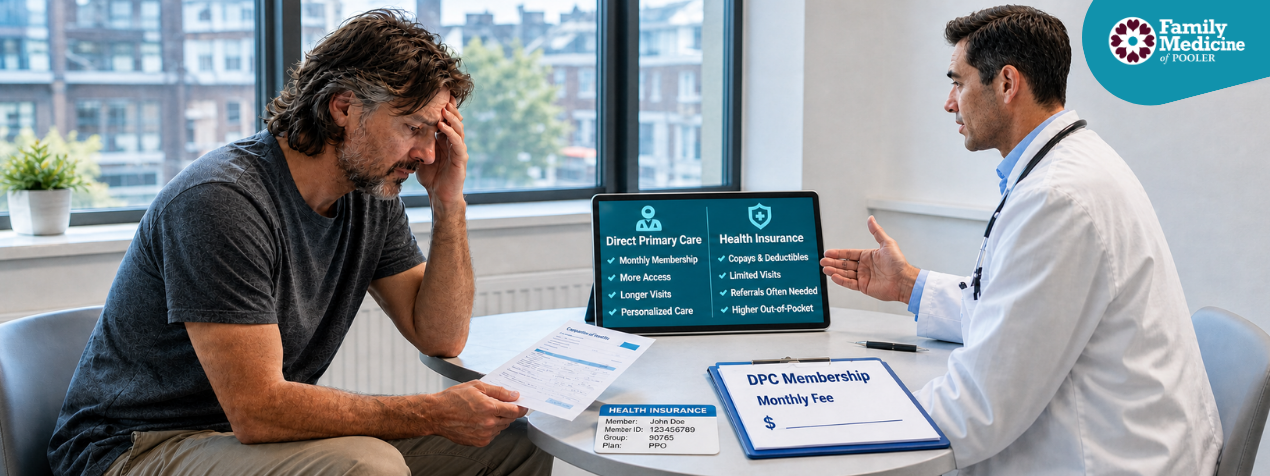
Direct primary care can be worth it if you already have insurance, but it depends on what you need from your doctor and whether the extra monthly cost fits your budget. If getting appointments, asking questions between visits, or managing an ongoing condition has been difficult, a DPC membership may offer value. If your current doctor is accessible and your insurance makes primary care affordable, the additional expense may be harder to justify.
You already pay for health coverage, so it is reasonable to ask what another healthcare payment would give you. The answer starts with comparing the care you receive today with what a particular DPC practice actually offers.
What Are You Paying for Beyond Your Insurance?
With direct primary care, you pay a recurring membership fee directly to a practice for a defined set of primary care services. The practice generally does not bill your insurance for those included services.
Depending on the clinic, membership may include:
- Routine checkups and sick visits
- Preventive care
- Chronic condition management
- Medication follow-ups
- Phone or messaging access
- Telehealth appointments
- Selected in-office tests and procedures
DPC practices often serve smaller patient populations, which can allow longer appointments and more direct communication. However, appointment availability, response times, and included services vary by practice.
For an insured patient, the question is whether those features improve everyday care enough to justify paying separately. A list of membership benefits means little unless it addresses something you need.
When Can DPC Be Worth the Extra Cost?
A membership may make sense when your current arrangement leaves you putting off care, struggling to get appointments, or paying substantial amounts for routine visits.
You need ongoing primary care.
Managing high blood pressure, diabetes, or another chronic condition can involve regular visits, medication reviews, and questions between appointments. Check whether those services are included and how follow-up works.
Getting an appointment is difficult.
If you regularly wait weeks to see your doctor, ask whether a DPC practice reserves appointments for sick members. Confirm what “same-day or next-day access” means in practice rather than assuming every appointment will be immediately available.
You want more opportunity to discuss concerns.
You may have several medications to review or questions that take time to work through. Ask about typical appointment lengths and whether you usually see the same physician.
Your primary care expenses are unpredictable.
A membership can make spending on included services easier to plan. This may be useful when visits are subject to your insurance deductible, although you should compare actual costs before assuming you will save money.
Even before you meet a deductible, insurance may provide negotiated rates for in-network care. A high deductible alone does not mean DPC will be cheaper.
When Might DPC Not Be Worth It?
DPC may offer limited additional value if you already have a doctor you trust, can get appointments when needed, and pay little for primary care through your insurance.
It may also be difficult to justify if:
- Another monthly payment would strain your budget.
- You rarely use primary care and are satisfied with your existing access.
- Your main expenses are specialist treatment, hospital care, or services outside the membership.
- The clinic charges separately for services you expected the membership to include.
Needing frequent healthcare does not automatically make DPC a good financial choice. Someone who mainly sees specialists may still have most of the same expenses after joining.
Likewise, someone who rarely visits a doctor may value convenient access, but that is a personal benefit rather than proof of cost savings.
How Do You Compare DPC Costs With Your Current Care?
Start with 12 months of membership fees, then add any enrollment fee and expected charges for services outside the membership.
Next, review what you actually spent on primary care over the past year. Use your insurance statements and bills where possible. Separate primary care costs from hospital, specialist, and other expenses that a DPC membership would not replace.
Here is a hypothetical comparison:
| Expense | Current primary care | DPC membership |
|---|---|---|
| Four included office visits | $30 copay each, totaling $120 | Included |
| Membership fee | None | $90 monthly, totaling $1,080 |
| Annual total for these items | $120 | $1,080 |
This example excludes insurance premiums, enrollment fees, tests, medications, and other services. It does not represent a specific clinic or insurance plan.
In this situation, DPC costs $960 more per year for the items shown. A patient might still choose it for appointment access or communication, but it would not be a saving on visit costs.
The calculation could look different for someone paying more out of pocket for repeated primary care visits. Even then, compare equivalent services and account for anything charged separately.
Keep your insurance premiums in the calculation. Joining DPC does not automatically reduce them. Also, do not assume membership payments count toward your insurance deductible or out-of-pocket limit. Confirm how your plan treats those payments.
How Does DPC Work Alongside Your Insurance?
You can use a DPC membership for included primary care while keeping insurance for eligible services outside the practice.
For example, your DPC doctor might evaluate a concern and recommend imaging or a specialist visit. Those outside providers bill separately. Your insurance may help pay, subject to its coverage, network, referral, and authorization rules.
Before joining, ask your insurer:
- Do I need to keep an assigned in-network primary care doctor?
- Will my plan accept referrals or orders from the DPC physician?
- Which labs, imaging centers, and specialists should I use?
- Do any recommended services require prior authorization?
These questions matter because a doctor recommending a service does not guarantee your insurer will pay for it.
DPC also does not replace health insurance for major medical expenses. Emergency treatment, hospital stays, surgery, and most outside specialist care fall beyond a primary care membership.
What Should You Ask Before Joining?
Ask the practice to explain how membership would work for the care you actually use.
For example: “I have blood pressure checks every few months, take two prescriptions, and occasionally need lab work. Which of those services would my fee include?”
Then confirm:
- Included care: Which visits, tests, and procedures are part of membership?
- Additional charges: What would you pay for medications, external labs, or other services?
- Appointment access: How soon can members usually get routine and sick appointments?
- Communication: Who answers messages, during what hours, and how quickly?
- Membership terms: Is there an enrollment fee, minimum commitment, or cancellation notice?
Ask for clear prices where available. Discounted lab work or medications may be helpful, but discounted does not mean included.
If you are considering Family Medicine of Pooler, discuss your usual healthcare needs with the team and review the membership alongside your insurance benefits.
DPC is worth considering when you can identify what the extra payment would improve. If it solves a recurring problem with your primary care and the cost is manageable, it may be worthwhile. If your current care already meets your needs, keeping your existing arrangement may make more sense.